Automotive
If you have comprehensive coverage, your California auto policy can pay for a cracked or chipped windshield, minus your deductible. A small chip repair is often covered with no deductible at all. You can choose who does the work, and you don’t have to take your car to a shop your insurer picks. In Orange County that means you can have a mobile technician come to your driveway or office, handle the paperwork with your carrier, and recalibrate your driver-assistance cameras in the same visit.
This guide walks through what a glass claim is, what your coverage pays, how to file, what to confirm about ADAS calibration, and how to avoid the mistakes that cost drivers money.
TL;DR
- In California, glass damage is paid under comprehensive coverage, which is optional. Check your declarations page before you call anyone.
- Repairs are often covered with the deductible waived. Replacements usually mean you pay your deductible, so compare it with the cost of the job.
- You choose the glass shop. Your insurer cannot require a specific one.
- Cars with lane-keeping, collision warning or similar features usually need ADAS recalibration after a new windshield, ideally in the same visit.
- Auto Glass Kings bills insurance directly and comes to you in Orange County, starting at 5 AM daily.
Table of Contents
- What a glass claim actually is
- Does California insurance cover windshield damage?
- Is it worth filing? A simple deductible check
- When repair is enough and when you need replacement
- What California law says about driving with a cracked windshield
- How to file an auto glass claim in Orange County, step by step
- ADAS calibration: confirm it before the work starts
- Costs by glass type
- Our perspective on glass claims
- Book a mobile glass claim visit
- After the install: what to do next
- FAQ
- Sources
What a glass claim actually is
A glass claim is a claim for damage to your car’s glass, filed under the part of your policy that covers non-collision damage. Rock strikes, falling debris, hail, vandalism and hitting an animal all fall in this category. Progressive explains that comprehensive coverage may pay for glass repair or replacement after falling debris, hitting an animal or other unexpected events, minus your deductible.
If another driver caused the damage in an accident, you can also choose to file against their insurance to cover the windshield, according to the same Progressive page.
Glass claims are narrower than most people assume. USAA notes that headlight, taillight, side marker and fog light damage is typically not handled as a glass claim. It may be covered elsewhere in your policy and would need to be reported as a regular auto claim. The glass claim usually covers windshield, side, rear and similar window glass.
Does California insurance cover windshield damage?
Only if you carry comprehensive. California does not require it, and the state’s minimum liability coverage pays for damage you cause to others, not for damage to your own car. If you only carry the legal minimum, a cracked windshield is yours to pay for.
If you do have comprehensive, the next question is the deductible. The California Department of Insurance explains in its auto guide that a deductible is the part of a loss you pay yourself, and that a higher deductible usually means a lower premium. Its example: with a $500 comprehensive deductible and $1,500 of storm damage, you pay the first $500 and comprehensive pays the remaining $1,000.
Here is how that plays out on glass:
- Chip repair: Many carriers waive the deductible. GEICO states that it will waive the deductible when you have your glass repaired, if you have the appropriate coverage. Progressive says that if your glass can be repaired rather than replaced, you won’t have to pay anything in most cases.
- Full replacement: Expect your comprehensive deductible to apply, unless your policy has a separate glass deductible or a $0 glass option. Progressive’s buyer guide says deductibles typically range from $100 to $2,000, and that some insurers offer no deductible on glass claims depending on the state.
The quickest way to know what you owe is to open your policy’s declarations page and look at the comprehensive line, then ask your agent whether glass has its own deductible.
If you own a vintage or specialty car, the coverage picture can differ because many collectors insure on separate policies. A guide to classic car insurance requirements explains when comprehensive applies and whether you pay a deductible, which is worth reading before you call about a cracked classic windshield.
Is it worth filing? A simple deductible check
Progressive’s guidance is that it generally makes sense to file when the repair costs more than your deductible. Its example: a $400 replacement with a $250 deductible means you pay $250 and the insurer pays the remaining $150.
Bring that logic to Orange County with a few steps:
- Find your comprehensive deductible on your declarations page.
- Get the job quoted. Our published repair range is $79 to $129. Windshield replacement has no flat published price because it depends on the vehicle, the glass and any calibration needed, so we quote it for your car.
- If the job costs more than your deductible, file. If it costs less, paying out of pocket may make sense, and you avoid a claim on your record.
- If it’s a chip that can be repaired, ask your carrier whether the deductible is waived. That is often the cheapest outcome of all.
Will a glass claim raise your rates?
It can, depending on your carrier and state. Progressive acknowledges that a comprehensive claim, including one for a chipped or cracked windshield, might increase a policyholder’s rate depending on the state. Rate treatment varies by company, so ask your agent before filing if you are rate-sensitive. Fixing a chip early also helps you avoid the larger replacement claim that a spreading crack can become.
When repair is enough and when you need replacement
Insurers and glass techs use similar rules of thumb. California Casualty says a windshield qualifies for replacement when the damage is larger than 6 inches, reaches the edge of the glass, or sits in the driver’s line of vision. USAA adds that damage smaller than a dollar bill is generally repairable, while four or more chips or cracks, or damage larger than 6 inches, points to replacement.
That is why timing matters. A chip left alone in Orange County’s heat and freeway vibration can grow into a crack. Our windshield chip repair service runs $79 to $129, and if you want to see how crack types affect the decision, we explain it in our guide to windshield crack types and repair rules.
What California law says about driving with a cracked windshield
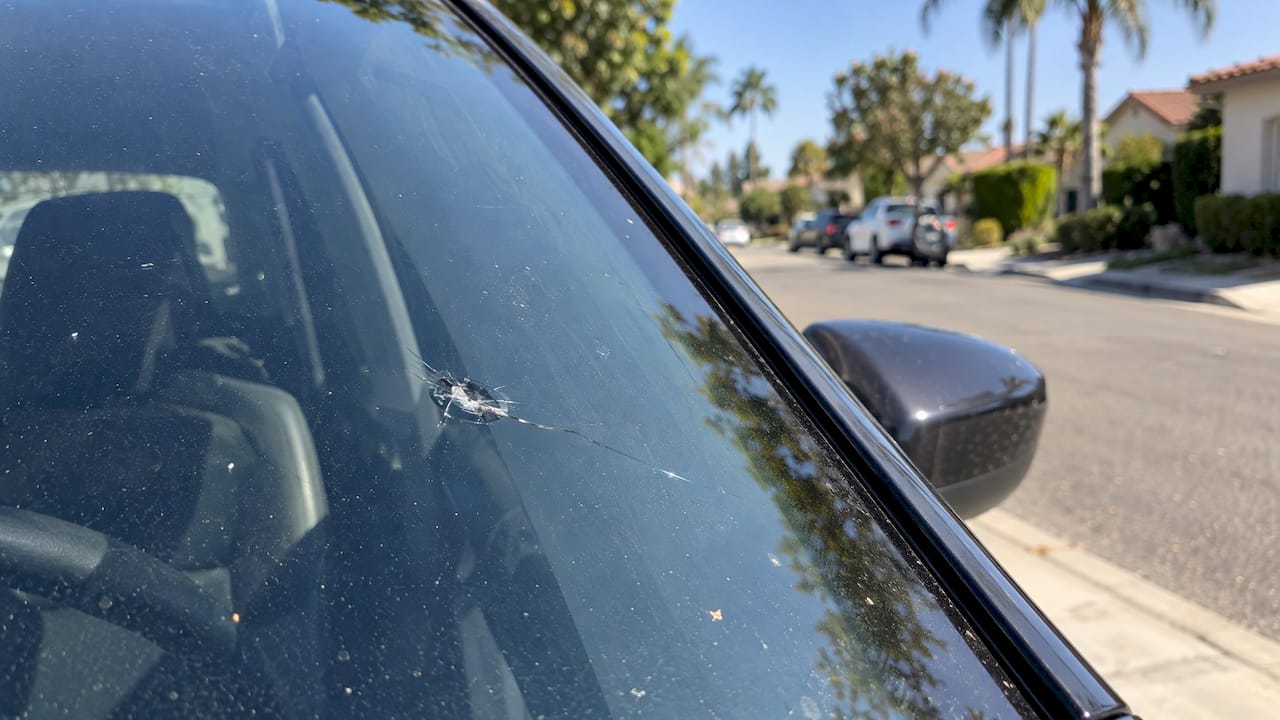
California Vehicle Code section 26710 makes it unlawful to drive on a highway when the windshield or rear window is so defective that it impairs the driver’s vision to the front or rear. An officer can direct you to make the window conform within 48 hours and may also arrest the driver, issue a notice to appear, or require evidence in court that it was fixed.
The statute sets no specific crack length. The test is whether the damage impairs your vision, so a crack across the driver’s sight line is the riskiest place for one. If you have damage there, schedule the fix now rather than waiting for your claim to be paid out. A mobile appointment is the fastest way to get back to legal.
How to file an auto glass claim in Orange County, step by step
- Photograph the damage. Take wide and close-up photos, including the crack’s position relative to the driver’s view. Note the date and what happened.
- Check your coverage. Confirm you have comprehensive and find the deductible. Ask whether glass has a separate deductible.
- Contact your insurer promptly. Progressive’s buyer guide recommends reaching out right after a loss, ideally within 24 to 48 hours, and notes that many insurers let you file through a mobile app.
- Choose your glass shop. The California Department of Insurance’s Auto Body Repair Consumer Bill of Rights states that you are entitled to select the shop, and an insurer shall not require repairs at a specific one. California Casualty’s claims FAQ says the same for glass: you may choose any repair facility, even if the carrier offers a referral line.
- Book the mobile visit. Give your claim number or policy information to the shop so it can bill your carrier directly.
- Expect a follow-up. The Department of Insurance’s accident guide notes that your insurer will contact you for details about the loss and may take a written or recorded statement.
- Keep the paperwork. You are entitled to an itemized written estimate and, when the job is done, a detailed invoice listing parts and labor and identifying parts as new, used, aftermarket, reconditioned or rebuilt, per the same Bill of Rights.
Be careful with what you sign
Be careful about signing an Assignment of Benefits, which lets a provider collect directly from the insurer. The Hartford warns that for glass damage it isn’t necessary, since glass is a relatively quick and low-cost repair, and that signing one could produce an inflated claim that drives up premiums. Read any form before you sign, and ask your shop to explain exactly what it covers. Direct billing means your shop works with your insurer on the payment. It should not require you to give up control of your claim.
ADAS calibration: confirm it before the work starts
If your car has lane-departure warning, automatic emergency braking, adaptive cruise or a forward camera, the camera behind the windshield has to be recalibrated after a new windshield goes in. USAA says that in most cases cars with advanced safety features like collision detection or lane assist need their sensors recalibrated after replacement, usually during the same visit.
Before you book, confirm three things:
- Does your car need calibration? Check your owner’s manual or ask us with your VIN.
- Does your policy cover it? Ask your insurer if calibration is paid as part of the glass claim.
- Will it happen in one visit? With us it does. All required calibrations are done in-house and on-site, so there is no second appointment and no trip to a dealership.
Our ADAS calibration runs $250 to $700 depending on the vehicle and system. If you want the technical background, we explain static versus dynamic calibration and what to expect from ADAS calibration in Orange County.
Costs by glass type
What you pay depends on which glass is damaged. Our published prices:
| Service | Our published price |
|---|---|
| Windshield repair (chip or small crack) | $79 to $129 |
| Side window replacement | From $189 |
| Back window replacement | From $350 |
| ADAS calibration | $250 to $700 |
| Windshield replacement | Quoted for your vehicle |
| Quarter and vent glass | Quoted for your vehicle |
Whether your insurer pays depends on your coverage. Many of our customers report paying nothing out of pocket once insurance is billed. For a deeper breakdown, see what you’ll pay for windshield replacement with insurance.
Our perspective on glass claims
We see the same pattern every week in Orange County: a driver finds a chip, waits, and ends up with a crack that needs a full replacement and a recalibration. The claim is rarely the hard part. The hard part is the logistics, which means a day without a car, a dealership appointment, and a second visit for ADAS.
That is why we built our service around doing everything in one visit. We come to your home, office or school pickup line, replace or repair the glass with OEM-quality materials, complete any required calibration ourselves, and bill your insurance directly. We start at 5 AM, so you can be on the road before your workday begins.
Every install carries a lifetime warranty. We believe a claim should feel like an errand you got done, not a project you had to manage, and we work with whatever vehicle you drive, from a daily commuter to a classic to a Tesla or Bentley.
Auto Glass Kings
Book a mobile glass claim visit
Auto Glass Kings handles the whole job where you are: windshield repair and replacement, side, back, quarter and vent glass, and in-house ADAS calibration, all with free mobile service across Orange County. We bill your insurance directly, include a lifetime warranty on every install, and start as early as 5 AM every day.
If you already know you need a new windshield, start with our windshield replacement page. For a chip, go to windshield repair. Not sure which? Reach us through autoglasskings.com and we will tell you which one fits your damage and your coverage.
After the install: what to do next
Once your glass is replaced, the adhesive needs time to cure. Follow the aftercare steps your technician gives you, and see our windshield replacement aftercare guide for the first 48 to 72 hours. Keep your invoice with your claim records, and if your carrier asks follow-up questions, send them the itemized invoice.
If you have side or rear glass damage from a break-in or a stray impact, the claim process is the same. We cover side window replacement and back window replacement on site, and we can also handle quarter and vent glass.
FAQ
What is a glass claim in auto insurance?
It is a claim for damage to your vehicle’s glass, usually paid under comprehensive coverage. It covers causes like road debris, hail, vandalism or hitting an animal. Lights are typically handled as a regular auto claim instead.
Does California require insurers to waive the deductible on windshield repairs?
There is no requirement we can point to, so it depends on your carrier and policy. Some companies, such as GEICO, say they waive the deductible when glass is repaired rather than replaced. Check your declarations page or ask your agent.
Can I use any shop for my claim?
Yes. California’s Auto Body Repair Consumer Bill of Rights says you have the right to select the repair shop, and an insurer can’t require a specific one. That includes a mobile glass company that comes to you.
Can a 12 inch crack in a windshield be repaired?
Usually not. Insurers generally point to replacement when damage is larger than 6 inches, reaches the edge of the glass or sits in the driver’s line of vision. A crack that long is a replacement candidate, so get it quoted promptly.
Does a glass claim count against me?
It can affect your renewal depending on your insurer and state. Progressive says a comprehensive claim, including a windshield claim, might raise a rate depending on the state. Ask your agent how your carrier treats glass claims before you file.
Sources
- Does Car Insurance Cover Windshield Damage? (Progressive)
- Windshield and Glass Claims (USAA)
- GEICO Glass and Windshield Insurance Claims
- Progressive First Time Car Insurance Buyers Guide
- California Department of Insurance: Automobile guide
- California Department of Insurance: Auto Body Repair Consumer Bill of Rights
- California Department of Insurance: So You’ve Had an Accident, What’s Next?
- California Casualty: Windshield Repair or Replacement
- California Casualty: Claims FAQs
- California Vehicle Code section 26710
- The Hartford: Outsmarting Glass Repair Scams
Recommended
- Windshield Replacement Orange County
- Auto Glass Replacement in Orange County: Cost, Process, and What to Expect
- Side Window Replacement Orange County
- Windshield Chip Repair Orange County
🎧 Listen to This Article
Share
Recent Posts
November 22, 2026
Auto Glass Coverage in California: What Your Policy Pays
How California auto insurance covers windshields, side glass and ADAS calibration, what deductibles mean, and what the 2026 glass law changes for you....
November 21, 2026
Bentley Windshield Sensors: What Sits Behind the Glass
Bentley windshield sensors explained: the camera, rain and light sensors behind the glass, what a replacement does to them, and how to get...
November 20, 2026
Urethane Smell in Your Car: What It Is and What to Do
A sweet, chemical smell after a windshield replacement is usually fresh urethane adhesive. Learn what causes it, how to ventilate safely and when...