Automotive
To file a windshield insurance claim, call your insurer or use its app or website, give your policy number, the date of the damage and your VIN, then book the glass work. Most glass damage is handled under comprehensive coverage. Many insurers waive the deductible when a chip is repaired instead of replaced. We are a mobile shop in Orange County, and we can bill your insurer directly and do the work in your driveway or at your office.
TL;DR
- Windshield damage is usually a comprehensive claim. Check your policy for a glass endorsement, which in some cases means no deductible.
- Have your policy number, the date of the damage and your VIN ready before you call.
- A chip or short crack that can be repaired often skips the deductible. Replacement usually carries one.
- If your car has driver-assistance cameras, the claim should include ADAS calibration after a replacement.
- We handle the paperwork with your insurer and come to you, from 5 AM daily.
Table of Contents
- Does your insurance cover a cracked windshield?
- What to have ready before you file
- How to file a windshield claim, step by step
- Deductibles: repair versus replacement
- Will a glass claim raise your rates?
- Repair or replace: what the insurer will look at
- ADAS calibration is part of the claim
- How long does it take?
- Perspective: why we handle the claim for you
- Let us handle your windshield claim
- Other glass your policy may cover
- FAQ
- Sources
Does your insurance cover a cracked windshield?
Usually yes, if you carry comprehensive coverage. Farmers explains that comprehensive can help pay for a windshield damaged by flying rocks, road debris, severe weather, falling branches, animal collisions, vandalism or break-ins. Progressive says that drivers with both comprehensive and collision are typically covered for glass repair, including a full replacement.
Liability-only policies generally do not pay for your own glass. If you are not sure what you carry, your declarations page lists your coverages and deductibles. Our own guide to comprehensive versus collision glass coverage walks through which one responds to which kind of damage.
Full glass coverage
Some policies add a separate glass endorsement. Allstate notes that full glass coverage may be available in some states, either inside comprehensive or as an add-on, and it can mean no deductible for windshield repair. Farmers adds that a few states have laws limiting or prohibiting windshield deductibles. Florida is the example Progressive cites, where deductibles are waived for broken windshields if you carry comprehensive.
California is not on that list as a rule for every policy, so read your own policy or ask your insurer whether you have glass coverage. If you do, the claim can be very simple. Our page on zero-deductible glass coverage explains how to spot it.
What to have ready before you file
A claim goes faster when you have the basics in hand. Westfield lists the policy number, the date of the incident and the vehicle identification number. Most carriers ask for the same three items.
Also get these together:
- Your VIN. It is on the lower corner of the dashboard on the driver’s side, visible through the windshield, and on your registration and insurance card.
- A few photos. Show the chip or crack, where it sits on the glass, and a coin or dollar bill for scale.
- Where the car will be. Mobile service means we can come to your home, workplace or a parking lot, so tell the insurer or us the address and a time window.
- Your deductible. Know the number so you can compare it with the repair or replacement cost.
You do not need a police report for a rock chip. If the damage came from vandalism or a break-in, ask your insurer whether it wants a report number.
How to file a windshield claim, step by step
- Check your coverage. Look for comprehensive, and for any glass endorsement or glass deductible that differs from your regular one.
- Photograph the damage. Take wide and close shots from inside and outside the car.
- Report the claim. Insurers take glass claims by phone, app or website. For example, Westfield accepts claims online or by phone through its glass service line.
- Say whether you want repair or replacement. The insurer or the shop will assess which one the damage calls for.
- Choose the shop. In most cases you can pick a shop that suits you. Tell the adjuster you would like a mobile provider and give us as the shop.
- Book the visit. We come to you, and we can start as early as 5 AM, so the job can be done before work or between school runs.
- Confirm ADAS needs. If your car has forward-facing cameras or sensors, make sure calibration is part of the job.
- Keep the paperwork. Save the invoice, the warranty and any calibration report.
If you would rather skip the phone tree, our guide for drivers on how to file an auto glass claim covers the process from our side of the counter.
Deductibles: repair versus replacement
The deductible is where most of the confusion sits. Three insurers say it the same way:
- GEICO states that broken glass is generally handled under comprehensive coverage, which is usually subject to a deductible, and that it waives the deductible when glass is repaired.
- Erie says that if the windshield can be repaired rather than replaced, the customer will not have to pay the comprehensive deductible.
- American Family notes that a repair may waive the deductible depending on your coverage, while a replacement will likely carry one.
The practical lesson: the sooner a chip is fixed, the more likely it stays a repair. A chip that spreads into a long crack becomes a replacement, and a replacement is where a deductible usually comes in.
What a repair costs us
Our windshield repair runs $79–$129. Replacement does not have a published price, because it depends on your glass, sensors and whether a calibration is needed. Many of our customers pay nothing out of pocket because we bill the insurer directly. For a side-by-side look, see the cost difference between windshield repair and replacement.
Comparing the cost with your deductible
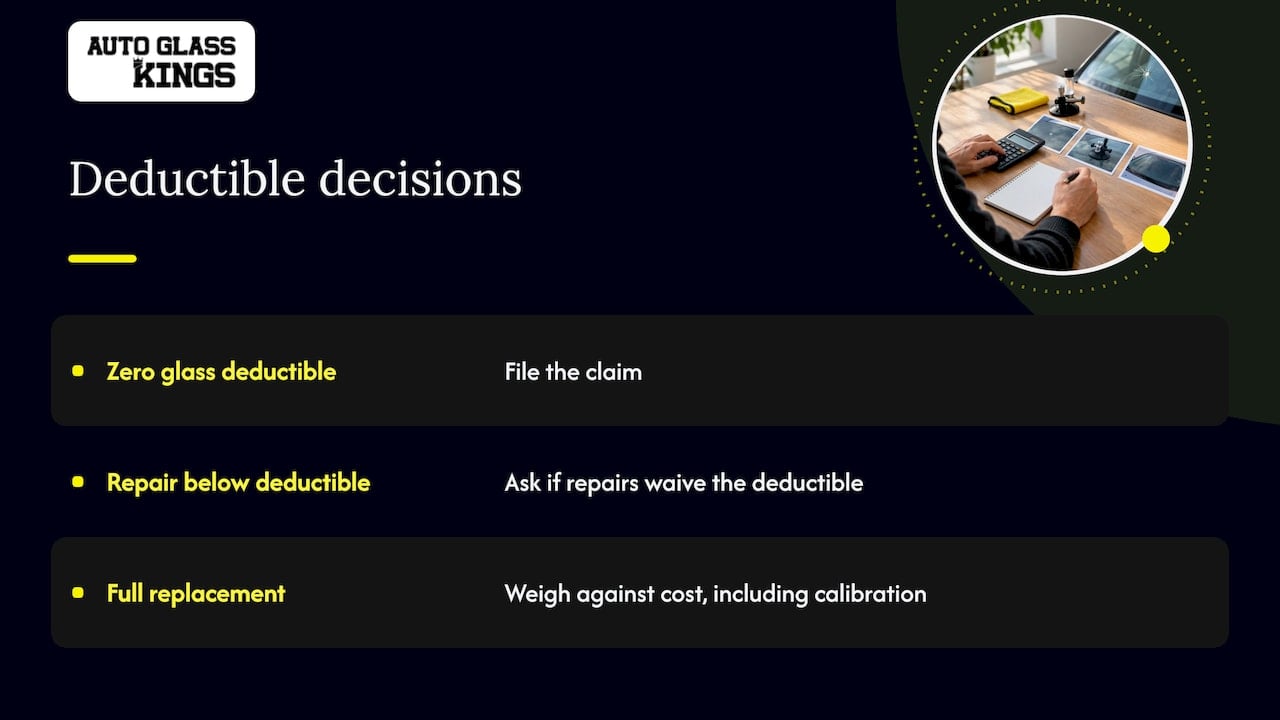
A simple rule helps. If your glass deductible is zero, file. If the deductible is higher than a repair price, ask your insurer whether it waives the deductible for repairs, which many do, as the quotes above show. If you are facing a replacement, your deductible is the number to weigh against the full cost, including calibration. Our page on windshield replacement cost with insurance lays out how the pieces add up.
Will a glass claim raise your rates?
Glass claims are usually treated lightly. American Family says that a windshield claim typically does not bring a surcharge, but a pattern of frequent claims could lead a company to see you as higher risk. Rules differ by carrier and state, so if this worries you, ask your agent how glass claims are rated on your policy before you file. Asking a general question does not open a claim.
Repair or replace: what the insurer will look at
Insurers apply size and location rules to decide. USAA says a windshield can be repaired if it has 3 or fewer chips smaller than 6 inches, and replacement is recommended for 4 or more chips or cracks, or damage over 6 inches. State Farm describes repairable damage as small breaks outside the area directly in front of the driver, fewer than 3 cracks, each under 6 inches. Erie’s rule of thumb is chips, nicks and cracks up to the length of a dollar bill.
The details of chip sizing are in our piece on windshield chip size limits. If you are looking at a chip right now, our windshield repair service is the quickest way to stop it from spreading.
Why it matters to fix it fast
This is a safety issue as well as a money one. Erie explains that a chip weakens the glass, that in a rollover the windshield helps keep the roof from collapsing, and that glass helps airbags deploy properly. If you wonder whether you can keep driving in the meantime, we cover that in driving with a cracked windshield.
ADAS calibration is part of the claim
If your car has automatic emergency braking, lane assist or forward collision warning, the camera behind the windshield has to see the road correctly. Mapfre notes that manufacturers require camera recalibration after a windshield replacement, so those systems keep working as designed.
Calibration is typically part of the covered job when the manufacturer calls for it, so mention it when you file. Our ADAS calibration costs $250–$700 depending on the vehicle, and we do it in-house during the same visit. You can read about the two methods in static versus dynamic calibration.
New disclosure rules for glass shops
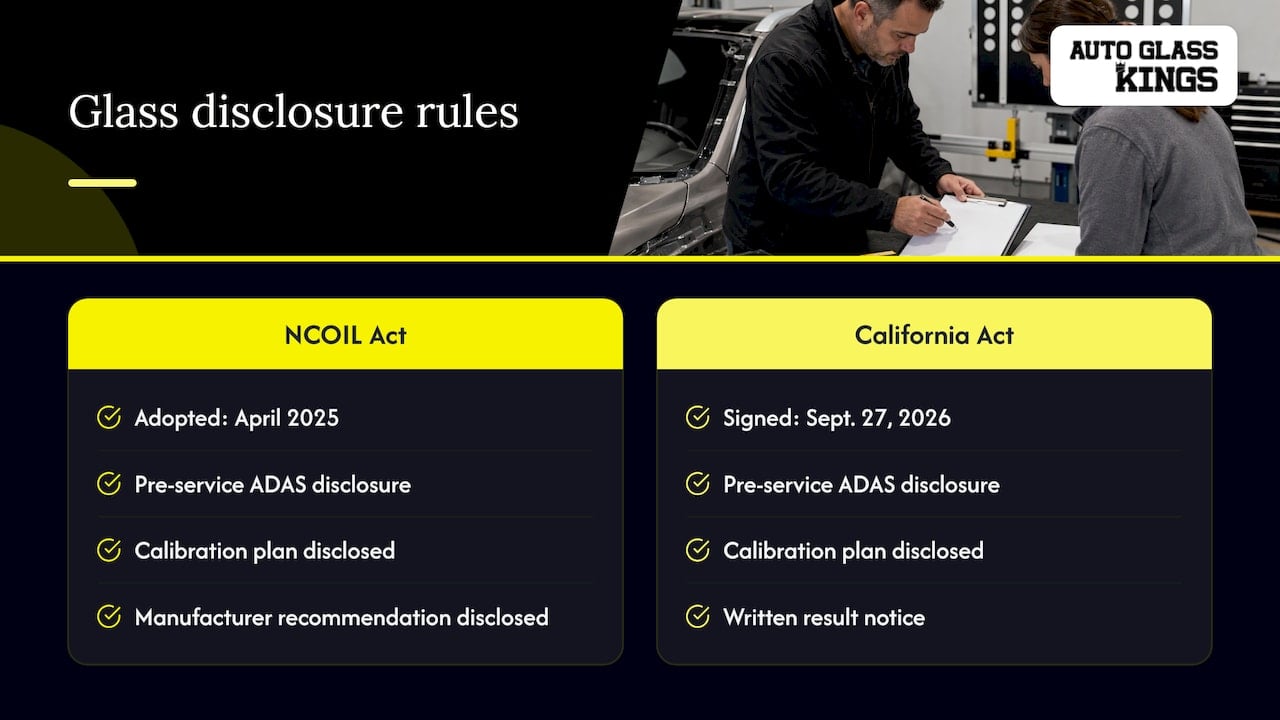
The rules around ADAS are tightening. The NCOIL Motor Vehicle Glass Model Act, adopted in April 2025, asks shops to tell the insured before service whether the vehicle has ADAS, whether calibration is recommended by the manufacturer, and whether the shop plans to perform it. It also calls for written notice of the result.
California followed. The state’s Motor Vehicle Glass Act was signed on September 27, 2026. It requires shops to disclose ADAS and calibration plans before service and give written notice of results. It also says customers should be advised to use a certified dealership or qualified specialist if calibration is unsuccessful. For you, that means one practical question when you book: will the shop do the calibration itself? Ours does, every time it is needed.
How long does it take?
Glass claims move quickly. State Farm says repairs may typically be completed within 48 hours of filing, with a shop repair taking 20 to 30 minutes. Erie adds that most chip repairs take about 30 minutes and the car is safe to drive right after. After a replacement, the technician advises you on safe drive-away time, which varies with weather and adhesive. Auto-Owners notes that replacements can take longer depending on scheduling, parts and whether recalibration is needed.
After a replacement, follow the technician’s instructions on washing and door slamming. Our windshield replacement aftercare guide covers the first 48 to 72 hours.
Perspective: why we handle the claim for you
Most drivers do not delay a glass claim because the glass is a small problem. They delay because the process looks like three errands: call the insurer, find a shop, then find a second place for the camera calibration.
We built Auto Glass Kings to remove those steps. We come to you, we start as early as 5 AM, we bill your insurer directly, and we complete the glass work and any required ADAS calibration in-house in a single visit. Most of our customers pay nothing out of pocket.
We use OEM-quality materials and put a lifetime warranty on every install. Our view is simple: a claim should take one phone call, and the car should leave our hands working the way it did before the damage, cameras included.
Auto Glass Kings
Let us handle your windshield claim
If you drive in Orange County, we make the claim the easy part. We are a mobile service, and the service call is free. We replace and repair windshields, side, back, quarter and vent glass, and we calibrate ADAS on modern vehicles, from everyday cars to Tesla and Bentley, and classics too.
Start with the page for your job: windshield replacement, windshield repair or ADAS calibration. Or go to Auto Glass Kings and book a time that fits your morning.
Other glass your policy may cover
Comprehensive can respond to more than the windshield. Side windows, back windows and quarter or vent glass broken in a break-in or by road debris are glass losses too. We list starting prices for side window replacement from $189 and back window replacement from $350. Quarter and vent glass has no published price, as it depends on the vehicle. For specifics see side window replacement, back window replacement and quarter and vent glass replacement. Tempered and laminated side windows differ, which is why we explain laminated side windows in a separate guide.
For a wider look at the process, our complete guide to auto glass replacement is a good next read.
FAQ
Should I file a claim for a small chip?
Often yes, because many insurers waive the deductible when a chip is repaired. GEICO and Erie both say so. Check your own policy, then book the repair before the chip spreads.
Do I have to use the shop my insurer recommends?
In most cases you can choose your own shop, though policies and state rules vary, so confirm with your insurer when you report the claim. Tell them you want a mobile provider. We can bill the insurer directly and handle the paperwork.
What information does the insurer ask for?
Expect to give your policy number, the date the damage happened and your VIN, as Westfield lists. Photos of the damage and the vehicle’s location speed things up.
Does my car need ADAS calibration after a replacement?
If it has cameras or sensors tied to safety systems, the manufacturer typically requires it, as Mapfre explains. We can check your vehicle and do the calibration in the same visit.
Will filing a glass claim raise my premium?
A single glass claim typically does not trigger a surcharge, according to American Family. Frequent claims of any kind can affect how a company rates you, so ask your agent if you are concerned.
Sources
- Farmers Insurance: Does Car Insurance Cover My Windshield?
- Progressive: Does Car Insurance Cover Windshield Damage?
- Allstate: Car Insurance for Windshield Damage
- Westfield: File a Personal Auto Claim
- GEICO: Glass & Windshield Insurance Claims
- Erie Insurance: Car Windshield and Glass Claims
- Erie Insurance: How to Handle a Windshield Repair
- American Family: Windshield repair and replacement insurance coverage
- USAA: Windshield and Glass Claims
- State Farm: Windshield and Glass Claims
- Auto-Owners: Glass Claims 101
- Mapfre: When to Repair or Replace a Damaged Windshield
- NCOIL Motor Vehicle Glass Model Act
- Body Shop Business: California Governor Signs California Motor Vehicle Glass Act
Recommended
- Drivers: File an Auto Glass Claim, Chip $50–$150, Mobile Billing
- What You’ll Pay: Windshield Replacement With Insurance, ADAS $150–$400
- Windshield Replacement Aftercare: 48–72 Hour Steps for US Drivers
- Auto Glass Replacement: A Complete Guide for US Drivers
🎧 Listen to This Article
Share
Recent Posts
November 22, 2026
Auto Glass Coverage in California: What Your Policy Pays
How California auto insurance covers windshields, side glass and ADAS calibration, what deductibles mean, and what the 2026 glass law changes for you....
November 21, 2026
Bentley Windshield Sensors: What Sits Behind the Glass
Bentley windshield sensors explained: the camera, rain and light sensors behind the glass, what a replacement does to them, and how to get...
November 20, 2026
Urethane Smell in Your Car: What It Is and What to Do
A sweet, chemical smell after a windshield replacement is usually fresh urethane adhesive. Learn what causes it, how to ventilate safely and when...